

Blogs
PW Consulting: Functional Sugar Market Hits $2.47B in 2025, Projected 6.2% CAGR to $3.81B by 2032
By PW Consulting, 2026-09-16
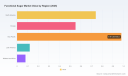
The Functional Sugar Market: Navigating the 2026 Growth Curve
The global landscape for functional sugars is undergoing a structural transformation. As consumer demand shifts steadily toward clean-label, low-calorie, and gut-health-supporting ingredients, manufacturers are recalibrating their portfolios to capture value in a high-growth segment. Our latest market research positions stakeholders to make informed decisions with a clear view of the macroeconomic trajectory and the competitive forces shaping the industry. Between 2020 and 2032, the market is projected to expand from 1.85 billion USD to 3.81 billion USD, reflecting a compound annual growth rate of 6.2 percent over the forecast period. This sustained expansion signals a durable shift rather than a transient trend, driven by regulatory approvals, supply chain maturation, and a broadening base of applications across food, beverage, and dietary supplement formats.
For executives evaluating capital allocation, product development pipelines, or market entry strategies in 2026, the window to act is narrowing. The pace of innovation among leading ingredient suppliers has accelerated, and the regulatory environment continues to evolve in ways that reward early movers with validated health claims and scalable production capabilities. This report distills those dynamics into a decision-ready framework, giving you the context needed to prioritize investments where demand signals are strongest and competitive pressure is most acute.
A Market on the Rise: Key Trajectory Signals for 2026
The historical record demonstrates a consistent upward climb. From 2020 through 2025, revenue grew each year, reaching 2.47 billion USD by 2025. Looking ahead, the forecast extends through 2032 and outlines a path that carries the total toward 3.81 billion USD. The progression is not uniform; it reflects a combination of volume growth, value-added formulations, and expanding geographic reach. By 2026, the market is expected to cross the 2.69 billion USD mark, establishing a new baseline for the decade ahead.
Several underlying drivers support this trajectory. First, the post-pandemic consumer emphasis on preventive health has elevated the role of gut microbiome support and metabolic stability as key purchase drivers. Functional sugars that deliver prebiotic benefits or moderate glycemic responses are increasingly embedded in everyday products, from breakfast cereals and snack bars to ready-to-drink beverages and capsule-based supplements. Second, manufacturing innovation has reduced the cost premium historically associated with specialized sweeteners, allowing brands to integrate functional sugars without sacrificing price competitiveness. Third, ingredient sourcing strategies are adapting to supply side realities; for example, EU sugar beet prices navigated a period of increase in the early 2020s before stabilizing in 2024 and softening during the first half of 2025, while USDA forecasts projected U.S. sugar production at a record 9.42 million short tons in the 2025/26 season. These supply factors influence cost structures and regional sourcing decisions, and they are examined in detail within the report to help procurement teams anticipate volatility.
Within this context, the buildup in capacity by major players is particularly noteworthy. Tate & Lyle expanded allulose production capacity by 35 percent in March 2025 to improve supply availability for low-calorie sweeteners, and Cargill has advanced fermentation-based functional sugar solutions that improve production efficiency for dietary supplement and food manufacturers. These moves signal confidence in sustained demand, but they also raise the bar for competitors and purchasers alike: access to premium functional sugars will increasingly depend on long-term partnerships and secured supply chains.
Rising from 1.85 Billion to 3.81 Billion: What the Growth Curve Means for Strategy
A market moving from 1.85 billion USD in 2020 to a projected 3.81 billion USD in 2032, at a CAGR of 6.2 percent, invites a straightforward question: where is the greatest value-creation potential concentrated, and how should organizations align their capabilities to capture it? The growth curve is not just a number; it is a signal of demand elasticity, category readiness, and regional maturity. As the base expands, differentiation becomes essential. The strongest performers are likely to be those that combine science-backed ingredient claims with consistent supply, regulatory compliance, and formulation flexibility.
Our analysis confirms that market leadership is fragmented rather than consolidated, a structural feature that creates room for niche positioning and targeted partnerships. The top three players collectively account for 34.5 percent of revenue, while the top five hold 49.2 percent. No single entity dominates, and the spacing between leading firms allows specialized suppliers to build durable presence in distinct applications or geographies. This dynamic is reinforced by the entry of regional and specialty manufacturers that bring formulation depth, localized sourcing, and proprietary processing methods. For brands evaluating suppliers, the implication is clear: supplier selection should weigh technical capability, claim substantiation, and capacity reliability alongside price.
The report frames these market-level signals in a way that supports scenario planning. Executives can use the trajectory data to model revenue ranges under different adoption timelines, assess the timing of product launches relative to regulatory milestones, and identify segments where the margin opportunity is widening fastest. Because the forecast spans multiple years, it also exposes inflection points where capacity additions or regulatory changes could alter competitive positioning, making now an ideal moment to review your roadmap against the data.
Competitive Landscape: How Tier-1 Innovators Are Defining the Next Wave
A resilient competitive field has emerged around functional sugars, with incumbents leveraging scale and specialists competing on formulation intelligence and claim support. The companies featured in this research represent a cross-section of strategies: some focus on core sweeteners with documented metabolic benefits, others emphasize fiber-based ingredients for digestive health, and several invest in sustainability as a differentiator. The report profiles each and compares their capabilities, recent moves, and positioning.
Tate & Lyle, headquartered in London, offers functional sugars including allulose and isomaltulose for blood sugar management and prebiotic benefits in dietary supplements and beverages. Its capacity expansion in allulose underscores a bet on consumer appetite for low-calorie, glycemic-friendly sweeteners. C.argill, based in Wayzata, provides fermentation-based functional sugar solutions with improved production efficiency for dietary supplement and food manufacturers, a route that can reduce cost and improve consistency. Ingredion, located in Westchester, launched a next-generation prebiotic sugar ingredient in January 2026 that improved digestive health performance by 24 percent for premium supplement formulations, an example of how formulation advances can accelerate adoption in higher-margin categories. ADM, in Chicago, supplies natural functional sugar ingredients to global beverage and food companies for North American operations, emphasizing broad reach and operational reliability. BENEO, in Karlsruhe, specializes in chicory root-derived functional carbohydrates and fibers for blood sugar management and sugar reduction, with regulatory recognition such as the FDA GRAS Notice 1242 for short-chain fructooligosaccharides issued in June 2025, which exempted specified uses from premarket approval.
On the plant-based and fiber side, Roquette Frères, in Lestrem, develops plant-based functional sugar and fiber ingredients for food, beverage, and supplement applications, and released its 2026 sustainable actions report in June 2026 highlighting biodiversity and nature initiatives in functional ingredient production. Tereos Group, in Origny-Sainte-Benoite, produces functional sugar solutions from beet and cane sources for sweetening and health-focused food products. Cosucra Groupe Warcoing, in Warcoing, extracts chicory root fibers such as PISANE™ as functional ingredients for sustainable nutrition and sugar alternatives. Nexira, in Rouen, supplies natural acacia and botanical extracts as functional ingredients for blood sugar control in supplements. In the low-calorie sweetener space, Samyang Corporation, in Seoul, manufactures allulose as a next-generation low-calorie functional sugar sweetener for beverages and snacks, while Matsutani Chemical Industry, in Itami, develops FIBERSOL® soluble dietary fiber and allulose for prebiotic and sugar-reduction applications.
Functional Chewing Gum Market
Across these players, three themes recur: diversification of sweetness and fiber platforms, investment in processing and capacity, and a sharper focus on validated health outcomes. The report maps these strategies to the segments and applications where they are most relevant, giving buyers a comparative lens to evaluate partnerships and procurement options with greater precision.
Functional Sugar Market
Segmentation Drivers: Ingredient Types, Application Breadth, and Regional Dispersion
The functional sugar market is not monolithic; it spans multiple ingredient types, application areas, and regional ecosystems, each with its own growth logic and competitive dynamics. The analysis segment the market by type, application, and region to surface where momentum is building and which combinations are likely to outperform.
By type, the market includes oligogaccharide, inulin, sugar alcohols, and other specialty categories. Oligosaccharides and inulin anchor the prebiotic narrative, while sugar alcohols and next-generation low-calorie sweeteners address glycemic management and calorie reduction. The "others" category captures emerging botanicals and fiber blends that continue to gain traction in premium formulations. The report examines each category substantively, without disclosing segment-level revenue shares, to help formulation teams match ingredient properties to functional goals and cost constraints.
By application, the breadth is broad and expanding. Food and beverage remain the largest usage base, where functional sugars are embedded in everyday products to deliver taste, texture, and health positioning. Dietary supplements constitute a significant and growing channel, where claims around digestive health and metabolic support are increasingly central to product identity. Pharmaceuticals and other applications contribute additional demand, often governed by stricter specifications and quality standards. The research outlines the differentiators across these applications, including regulatory requirements, formulation compatibility, and the strength of consumer demand signals, to guide category strategy and packaging decisions.
By region, the dispersion reflects differences in consumer preferences, regulatory frameworks, and supply infrastructure. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The report provides qualitative context on regional momentum drivers and sourcing patterns, again withholding exact split percentages, so that readers can calibrate their geographic focus to the most relevant growth engines without pre-judging local execution challenges.
Two regulatory developments frame part of this regional picture. EFSA extended the use of isomalto-oligosaccharide as a novel food under Regulation (EU) 2015/2283, a step that broadens the application canvas for certain prebiotic ingredients in Europe. In parallel, FDA granted GRAS notice 1242 for short-chain fructooligosaccharides from BENEO for use in certain foods, exempting those specified uses from premarket approval and simplifying formulation pathways. Together, these moves illustrate how regulatory milestones can unlock new product possibilities and influence regional prioritization.
Formulation and Sourcing Realities: What Operational Teams Need to Know
Turning market opportunity into commercial reality requires attention to the mechanics of formulation and sourcing. Functional sugars must perform not only as health-forward ingredients but also as contributors to taste, mouthfeel, stability, and shelf life. Each category presents trade-offs. Oreosaccharide and inulin can deliver prebiotic functionality and fiber content, but their behavior in different matrices varies; sugar alcohols offer sweetness profiles and glycemic moderation, yet their inclusion levels must be managed carefully; allulose and related low-calorie sweeteners can replicate sugar-like taste with lower caloric impact, but supply availability and cost remain important considerations for high-volume programs.
From a sourcing standpoint, the ability to secure consistent quality and volume is increasingly tied to supplier investment in processing efficiency and capacity. Cargill's fermentation-based solutions, for instance, reflect a broader industry shift toward more efficient production routes that can support scale without sacrificing quality. Meanwhile, sustainability is moving from a narrative element to an operational one: Roquette's 2026 sustainable actions report underscores biodiversity and nature initiatives as part of functional ingredient production, a signal that procurement teams may increasingly evaluate suppliers on environmental performance alongside cost and reliability. The report details the operational considerations relevant to each major ingredient route and supplier type, helping teams weigh formulation goals against supply continuity and total cost of ownership.
Regulatory alignment is another operational thread. The EU sugar beet price trajectory, the record U.S. sugar production forecast, and the evolving status of novel food approvals all influence cost structures and formulation options. By synthesizing these variables, the research equips teams to anticipate changes and adjust sourcing strategies before they become reactive.
Turn Insights into 2026 Decisions: The Full Intelligence Awaits
The functional sugar market is positioned for a sustained run of growth, with a clear upward trajectory, an active competitive field, and a regulatory environment that continues to open new possibilities. The report translates these macro trends into actionable intelligence, covering market sizing across historical and forecast years, segmentation by type, application, and region, competitive profiling of leading and emerging players, and the latest industry developments that could affect sourcing, formulation, and go-to-market timing in 2026 and beyond. It is designed to support multiple use cases: portfolio planning, supplier selection, market entry evaluation, pricing strategy, and long-range scenario modeling.
Because the decision space is competitive and time-sensitive, partial visibility carries risk. The report delivers the full segmentation detail, including regional breakdowns, application splits, and type-level analysis, alongside company comparisons and regulatory context, so that your team can act with precision. The complete intelligence is available on the source page; accessing it will give you the granular data needed to benchmark opportunities, validate assumptions, and set priorities for the year ahead.
Now is the moment to align your strategy with the data. As the market moves toward the 2026 baseline and beyond, organizations that combine strong formulation insight with reliable supply and clear health claims will be best placed to capture value. The research provides the foundation; your next step is to secure the full intelligence and translate it into concrete actions.
For detailed analysis of this topic, please visit the official page: Functional Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LNG Liquefaction Market Hits $215M in 2025, Projected 8.2% CAGR Through 2032
By PW Consulting, 2026-09-16
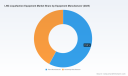
Strategic Intelligence for the LNG Liquefaction Equipment Market 2026: A PW Consulting Strategic Brief
As global energy trade realigns around natural gas security, flexible supply chains, and decarbonization pathways, the LNG liquefaction equipment sector has transitioned from a cyclical capital goods segment to a structural enabler of export diversification and buyer-side procurement resilience. PW Consulting’s latest market research release examines the full architecture of this market, providing executives, investors, and procurement strategists with a decision-grade intelligence framework calibrated for 2026 and the forecast horizon through 2032.
LNG Liquefaction Equipment Market
This article serves as a strategic preview of the complete report. It synthesizes the observable macro trajectory, the structural segmentation patterns, the competitive theater now being redefined by recent contract executions, and the operational dynamics that are reshaping cost, schedule, and technology selection in liquefaction programs. It is designed to demonstrate the analytical depth of the full dataset while preserving the exact segmentation figures, regional share distributions, and granular revenue breakdowns that our clients rely on for capital allocation, competitive benchmarking, and commercial positioning.
The 2026 Growth Trajectory: From Post-Pandemic Recovery to Structural Expansion
The market for LNG liquefaction equipment has moved decisively beyond the volatility of the early 2020s. The historical record shows a measured recovery across the 2020 to 2025 period, followed by an acceleration that establishes a robust baseline heading into the forecast window. According to the full research dataset, total market revenue has expanded from 163.15 million USD in 2020, through 177.66 million USD in 2021 and 180.05 million USD in 2022, to 183.07 million USD in 2023, climbing further to 201.3 million USD in 2024 and reaching 215.0 million USD in 2025. This progression reflects not only the restoration of project delays and supply chain normalization, but the emergence of sustained demand for liquefaction systems across both greenfield export capacity and mid-tier modular deployments.
Looking forward, the forecast period from 2026 to 2032 charts a clear path of compounding growth. The model projects revenue advancing to 236.46 million USD in 2026, 251.25 million USD in 2027, and 263.25 million USD in 2028, before an inflection step-up to 300.93 million USD in 2029, 322.5 million USD in 2030, 349.2 million USD in 2031, and 373.44 million USD in 2032. This trajectory is underpinned by a forecast CAGR of 8.2%, a rate that positions the liquefaction equipment segment as a disciplined growth market rather than an episodic boom cycle. For strategic planners, the significance of this 8.2% CAGR lies in what it implies about capital intensity, technology refresh cycles, and the competitive urgency of securing preferred equipment slots in late-2020s train expansions.
The full report contextualizes these headline numbers within a broader analytical architecture that explains the timing, magnitude, and structural logic of the 2029 step-change. Rather than presenting raw figures in isolation, the study maps them against contracting pipelines, modularization economics, train-scale dynamics, and vendor capacity constraints, transforming the top-line numbers into a decision-support system for capacity planning, partnership strategy, and risk-weighted procurement horizons.
Inside the Research: What Decision-Makers Will Find in the Full Report
A market research deliverable earns its strategic value only when it translates macro trends into actionable intelligence. The full PW Consulting study is structured to support that translation. It moves beyond a single aggregate view and decomposes the market into the operational, manufacturing, and infrastructure dimensions that determine real-world competitive outcomes.
The report provides a multi-dimensional segmentation framework that covers system-level equipment architectures, equipment manufacturing pathways, plant size classifications, and regional deployment patterns. This structure allows readers to isolate demand drivers across refrigerant compression, pumping and storage, power systems, and auxiliary categories, and to understand how plant configuration choices, modular versus stick-built construction philosophies, and plant sizing strategies influence both equipment mix and commercial positioning.
Within the plant-size lens, the dataset examines distinct deployment profiles, including small-scale LNG facilities, mid-scale plants, large export-oriented complexes, and floating LNG platforms. Each category carries different procurement patterns, technology preferences, cadence of equipment orders, and competitive access barriers. The research evaluates how these profiles interact with project financing structures, liquefaction cycle selection, and the increasing role of scalable modular solutions in compressing delivery timelines.
At the equipment manufacturing level, the analysis distinguishes between plant manufacturers and assembly manufacturers, clarifying the division of responsibility, integration risk, and commercial leverage that defines the current supply chain. This distinction is essential for procurement teams seeking to balance technology ownership against fabrication capability, for investors assessing vertical integration strategies, and for operators evaluating EPC partnerships with embedded equipment supply relationships.
The regional architecture of the market is equally critical. The full report covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, mapping where demand is concentrated, where equipment supply is scaling, and where project execution dynamics are most likely to generate near-term procurement pressure. The research avoids superficial regional rankings and instead examines the structural conditions that differentiate market access, lead-time expectations, and competitive intensity across geographies.
Beyond segmentation, the study integrates competitive profiling, recent contract executions, technology adoption patterns, modularization trends, labor and fabrication dynamics, and infrastructure developments that shape the competitive playing field. It is designed to be read alongside internal capital models, procurement planning cycles, and technology roadmaps, giving executives a common reference point for comparing vendor propositions, negotiating equipment package scopes, and anticipating bottlenecks.
Competitive Theater: Who Shapes the Liquefaction Equipment Landscape in 2026
The competitive environment in LNG liquefaction equipment is defined by a blend of proprietary process technology providers, primary equipment suppliers, modular solution developers, and large engineering-procurement-construction integrators. Market concentration, as captured in the full dataset, reflects a landscape where the top players collectively command a significant but not dominant share of revenue, leaving substantial space for differentiated capability, niche technology positioning, and regional execution strength. The CR3 and CR5 concentration metrics in the report provide an evidence-based starting point for understanding how competition is structured and where entry, partnership, or displacement opportunities may emerge.
Honeywell remains a central force in liquefaction process technology. Its equipment portfolio and cycle solutions are widely deployed across major export projects, anchoring its role in the refrigerant compression and heat exchange architecture that underpins liquefaction trains. The company’s technology footprint is reinforced by recurring selection in new train awards and its established presence in global LNG production workflows.
Baker Hughes operates as a core primary equipment supplier, with a focused position in refrigerant turbo compressors and gas turbine power systems that supply the mechanical and energetic core of liquefaction facilities. Its product relevance extends across export-oriented plants where reliability, efficiency, and long-term service integration are critical to project economics.
Technip Energies brings a distinct angle through modular liquefaction engineering and standardized SnapLNG concepts, alongside full engineering support for export terminals and liquefaction plants. Its approach reflects the broader industry shift toward scalable, repeatable, and faster-to-deploy plant configurations, making it a relevant benchmark for operators evaluating modular versus conventional delivery modes.
Kiewit and Bechtel anchor the large-scale execution side of the market. Both firms lead EPC programs for major LNG liquefaction and export projects, with responsibilities spanning module integration, pretreatment, pipe racks, process technology integration, and full facility construction. Their roles matter because the boundary between equipment supply and EPC execution increasingly shapes commercial risk, schedule certainty, and the strategic value of early equipment-selection decisions.
What gives this competitive set strategic importance in 2026 is not static market share, but the way recent contracts are revealing shifting alliances, modular technology adoption, and equipment-package contracting. These patterns are not decorative details; they inform pricing power, slot availability, technology preference, and the likelihood of localized fabrication versus global supply. The full report unpacks these competitive signals in depth, using recent project activity as a lens on where capabilities are being monetized and where competitive gaps may open.
2026 Activity Snapshot: What Recent Contracts Reveal About Market Direction
Recent developments in liquefaction projects are already reshaping how equipment suppliers, EPC firms, and operators interact across the value chain. The activity observed in early 2026 provides a forward-looking signal of execution priorities, technology choices, and fabrication strategies that directly affect equipment demand.
Technip Energies’ recent EPC contract execution for a 9.5 MTPA export facility reflects the continued scaling of modular-capable engineering solutions in large export infrastructure. The award underscores how modular liquefaction concepts are being embedded into substantial projects, influencing scope boundaries, equipment package structures, and delivery sequencing.
Honeywell’s technology supply agreement for Rio Grande LNG Train 4 and Train 5 demonstrates the continued relevance of established coil-wound heat exchanger equipment and C3MR process technology in high-profile export expansions. Selection of this type reinforces the importance of proven liquefaction cycle architecture in securing long-cycle export train awards, and it signals sustained demand for high-efficiency heat exchange and associated equipment packages.
Kiewit’s lump-sum turnkey EPC execution for a Texas LNG facility, including module fabrication for liquefaction, pretreatment, and pipe rack systems, highlights the intensifying role of self-performed work and integrated module fabrication in controlling schedule and cost outcomes. When a single EPC entity manages both on-site execution and off-site module fabrication, equipment procurement timing, coordination risk, and fabrication capacity become strategic variables rather than background logistics.
Baker Hughes’ additional order for primary liquefaction equipment on Rio Grande LNG Train 5, including gas turbines and centrifugal compressors, further illustrates how core rotating and compression equipment continues to anchor project schedules and equipment package value. These orders reveal the layering of equipment commitments within multi-train programs and the importance of aligning equipment delivery with modular construction milestones.
Beyond contract awards, the surrounding operational context matters. Module fabrication for liquefaction, pretreatment, and pipe rack systems is proceeding in Texas, reflecting localized fabrication strategies that can reshape lead times and labor deployment. The Rio Grande LNG project’s phased construction across multiple trains demonstrates the modular EPC approach in practice, with successive train progression creating a cadence of recurring equipment and integration demands. Technology adoption is another structural signal: one major equipment provider’s liquefaction technology is reported to be used in nearly two-thirds of global LNG fuel production, reinforcing the gravitational pull of established cycles in new selection decisions. Meanwhile, modular scalable solutions are increasingly delivering large tonnages of LNG modules as part of standardized liquefaction train offerings, tightening the link between modularization capability and competitive differentiation.
Taken together, these developments indicate that 2026 is a year when execution logic is shaping equipment market outcomes as much as project announcements are. The full report builds this context into a structured competitive reading that helps clients anticipate where bottlenecks, leverage points, and partnership opportunities will arise.
Strategic Implications for 2026 Decision-Making
For executives navigating LNG liquefaction equipment markets, 2026 is not simply a forecast year; it is a planning inflection point. The combination of an 8.2% CAGR, a stepped revenue path into the late 2020s, and an increasingly modularized, contract-dense competitive environment means that strategic decisions made now will influence equipment access, technology positioning, and cost outcomes across the 2026 to 2032 horizon.
Procurement teams need to understand where equipment demand is being concentrated by train configuration, plant size strategy, and modularization choice, and how those choices alter vendor leverage. Investors require segmentation visibility not merely to assess size, but to judge which system categories, manufacturer types, and plant-size segments are likely to see the strongest compounding demand and the most intense competitive contestation. Competing firms need competitive intelligence that goes deeper than headline company profiles to reveal how recent contracts, fabrication strategies, and technology selection patterns are redrawing the practical boundaries of market access.
The full PW Consulting report is designed to support all of these decisions. It gives readers the structure, evidence, and analytical language needed to evaluate equipment package scopes, prioritize manufacturing and partnership relationships, and align capital and procurement strategies with the underlying shape of the market.
Helium Liquefier Market
Why the Full Report Matters
This article provides the strategic frame and the visible portion of the analysis. The complete research report goes further. It delivers the segmentation breakdowns that reveal how system types, equipment manufacturer categories, plant size profiles, and regional markets interact to shape total demand; it presents the exact market size progression and concentration metrics that anchor scenario planning; it profiles the core companies with competitive context and recent activity integration; and it translates project-level developments into procurement, technology, and execution implications that can be applied across internal decision processes.
Most importantly, the full report preserves the precision that strategic planning requires without diluting it into oversimplified rankings. It is built for teams that need to compare vendor propositions, assess scope boundaries, forecast equipment ordering windows, and understand how competing modular and EPC strategies are reshaping the commercial landscape.
For executives, investors, procurement leaders, and competitive strategists preparing for 2026 and beyond, the complete PW Consulting LNG Liquefaction Equipment Market research is the next step in converting market intelligence into commitment-ready strategy. Explore the full dataset and segmentation detail to gain the complete view needed for capital, contract, and competitive decisions.
For detailed analysis of this topic, please visit the official page: LNG Liquefaction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The North America Mesh Gateway Market exhibits continuous revenue expansion, from USD 870 Million in 2020 to a forecasted USD 4,350 Million by 2035, reflecting an impressive CAGR driven by IoT adoption, smart device penetration, and modernization of urban and industrial infrastructure. The revenue trend shows steady annual progression, with accelerated growth from 2025 onward as advanced wireless technologies, hybrid solutions, and edge-enabled gateways gain market traction. Notably, significant revenue spikes align with major telecom operators and enterprises deploying large-scale mesh solutions for smart cities, manufacturing, and healthcare during the late 2020s and early 2030s.
Read More - https://bussinessinsights.com/research-report/north-america-mesh-gateway-market
Smart homes lead the applications segment in 2025, constituting 32% of the North America Mesh Gateway Market, propelled by widespread consumer demand for seamless, scalable home automation and security systems. Industrial automation follows with 27%, as factories and logistics centers integrate mesh networks for equipment monitoring, predictive maintenance, and process optimization. Smart cities capture 17%, reflecting substantial investments in connected infrastructure and public safety. Healthcare, transportation, and retail applications collectively make up the remainder, highlighting growth in telehealth, urban mobility, and digital retail experiences. These shares underscore the market's dual consumer and enterprise orientation, positioning mesh gateways as foundational elements in next-gen IoT and automation networks.
Request Free Sample- https://bussinessinsights.com/request/energy-and-power/north-america-mesh-gateway-market
Frequently Asked Questions
Who are the key players in North America Mesh Gateway Market industry?
Key players in the North America Mesh Gateway Market include Cisco Systems, Qualcomm Technologies, Digi International, Texas Instruments, and Hewlett Packard Enterprise. These companies lead through innovative networking solutions, extensive R&D investments, and strong distribution channels, making significant contributions to the adoption of mesh gateways across diverse industry verticals.
What is the North America Mesh Gateway Market growth?
The North America Mesh Gateway Market is experiencing robust growth, driven by rising IoT deployment and smart city initiatives. For instance, Cisco has reported increased sales of its mesh gateway solutions, enabled by demand for enhanced wireless coverage and the integration of IoT devices across sectors.
Which segment accounted for the largest North America Mesh Gateway Market share?
The smart home applications segment holds the largest share in the North America Mesh Gateway Market. Mesh gateways are widely adopted in residential networks to ensure seamless connectivity, support numerous smart devices, and facilitate advanced automation, driven by increasing consumer preference for smart living environments.
Thanks & Regards,
priya
sales@bussinessinsights.com
North America Substation Automation Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The North America Substation Automation Market is projected to grow significantly, with revenue increasing from $3,800 Million in 2020 to $8,950 Million by 2035. This sustained growth is attributed to continuous investments in smart grid deployment, grid reliability, and integration of automation technologies into both new and existing substations. The upward revenue trend highlights market acceptance of advanced solutions and the criticality of robust power infrastructure amid rising electrification and renewable integration.
Read More - https://bussinessinsights.com/research-report/north-america-substation-automation-market
The transmission sector leads the substation automation market with a 39% share in 2025, underpinned by grid modernization projects in the US and Canada. Distribution applications follow at 27%, while industrial and generation segments contribute 20% and 14% respectively. Growth within transmission is driven by investments in cross-border interconnection and national grid upgrades, enabling improved load balancing and outage protection. The distribution segment is expanding as utilities embrace automation for reliability and efficiency gains. These trends reflect industry focus on both large-scale grid infrastructure and localized distribution automation.
Request Free Sample- https://bussinessinsights.com/request/energy-and-power/north-america-substation-automation-market
Frequently Asked Questions
Who are the key players in North America Substation Automation Market industry?
The key players in the North America Substation Automation Market include ABB Ltd., Siemens AG, Schneider Electric SE, General Electric, and Eaton Corporation. These companies are recognized for their advanced technology offerings, wide product portfolios, and established presence in the region’s power automation sector.
What is the North America Substation Automation Market growth?
The North America Substation Automation Market has witnessed significant growth, driven by utilities’ modernization initiatives. In 2023, Schneider Electric reported increased demand for smart grids and digitalized substations, contributing to the region's robust market expansion at a CAGR of over 6%.
Which segment accounted for the largest North America Substation Automation Market share?
The transmission segment accounted for the largest share of the North America Substation Automation Market. This is attributed to the ongoing investments in grid upgrading and expansion by utility companies to enhance transmission reliability and accommodate increasing renewable energy integration.
Thanks & Regards,
priya
sales@bussinessinsights.com
The revenue analysis for the North America security cameras market reveals substantial growth from USD 7,250 million in 2020 to an estimated USD 18,750 million by 2035. This expansion is driven by increasing investments in smart surveillance, IoT integration, and advanced analytics. Notably, market revenue reached approximately USD 10,800 million in 2025, reflecting accelerated adoption in both commercial and residential segments. The compounded effects of regulatory compliance, urban development, and security modernization are expected to sustain double-digit growth rates into the late 2020s. Enterprises, governments, and critical industries are collectively contributing to the robust revenue trajectory, with further upside expected from ongoing innovation and value-added services.
Read More - https://bussinessinsights.com/research-report/north-america-security-cameras-market
The market is segmented by applications in 2025 with Commercial use leading at 36%. Residential makes up 22%, driven by the surge in smart home security adoption, especially post-pandemic. Industrial applications account for 17%, as factories and warehouses invest in perimeter and asset protection. Government comprises 13%, with ongoing public safety investments. Transportation stands at 7%, reflecting secure transit infrastructure needs, and Others hold a 5% share. The trend highlights the prominence of the commercial sector, underpinned by retail, hospitality, and banking security requirements. Residential and government sectors are catching up fast due to increasing public awareness and policy-driven adoption of surveillance solutions.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/north-america-security-cameras-market
Frequently Asked Questions
Who are the key players in North America Security Cameras Market industry?
The top five key players in the North America Security Cameras Market are Hikvision, Dahua Technology, Axis Communications, Bosch Security Systems, and Honeywell International. These companies drive innovation with advanced surveillance solutions, extensive distribution networks, and strong R&D, ensuring market leadership and extensive security camera product portfolios.
What is the North America Security Cameras Market growth?
The North America Security Cameras Market has seen robust growth, driven by increasing smart city initiatives and demand for remote monitoring. In 2023, companies like Axis Communications reported growth in network camera sales due to advancements in AI-powered surveillance and rising investments in public safety infrastructure.
Which segment accounted for the largest North America Security Cameras Market share?
The commercial segment accounted for the largest share of the North America Security Cameras Market. Applications in retail, banks, offices, and industrial facilities have driven adoption, with businesses prioritizing advanced security solutions to prevent theft, monitor premises, and comply with regulatory guidelines.
Thanks & Regards,
priya
sales@bussinessinsights.com
PW Consulting: Intelligent Excavator Market to Hit $2.1B in 2025, Surge 24.54% CAGR Through 2032
By PW Consulting, 2026-09-16
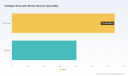
The Intelligent Excavator Market: Strategic Intelligence for 2026 Decision-Makers
Executive Overview: Why This Study Matters Now
The heavy machinery sector is undergoing a structural transformation as connectivity, automation, and precision control redefine how earthmoving assets are deployed. Intelligent excavators now sit at the center of this shift, merging advanced electrohydraulic architectures, real-time sensor integration, and operator assistance systems into platforms that compress rework, improve grade accuracy, and elevate site safety. For executives evaluating capital allocation, fleet modernization, technology partnerships, and supply chain strategy, the Intelligent Excavator Market represents both a growth vector and a complexity trap. The difference between capturing value and being disrupted lies in the quality of the intelligence underpinning strategic choices.
This market research study, published by PW Consulting, delivers a comprehensive view of the intelligent excavator landscape across the 2020 to 2032 horizon. Drawing on a rigorous base year of 2025 and a structured forecast window extending through 2032, the report is designed to give leadership teams a disciplined foundation for 2026 planning. Rather than offering static snapshots, the analysis traces the trajectory from $0.7 million in 2020 to $2.1 million in 2025, and projects sustained expansion toward $9.76 million by 2032, supported by a compound annual growth rate of 24.54%. These macroeconomic signals frame a market that is scaling rapidly, but they also underscore the need for deeper, decision-grade insight into where value is being created and how competitive advantage is being secured.
This article previews the strategic architecture of the full study. It highlights the market dynamics, competitive configurations, and operational content that matter most to decision-makers, while deliberately leaving the granular segment breakdowns for the complete report. The goal is to demonstrate the scope and analytical depth available, and to guide leaders toward the full intelligence package where they can act with confidence.
Market Trajectory and the Shape of the Opportunity
Any credible strategy for intelligent excavators must begin with a clear picture of market scale and momentum. Over the historical window from 2020 through 2025, revenue expanded from $0.7 million to $2.1 million, reflecting the early acceleration of smart machine adoption across multiple end-use environments. The forecast period from 2026 to 2032 extends this expansion into a phase of more mature, systemic growth, with projected revenue rising from $2.69 million in 2026 to $9.76 million in 2032. This path is not merely a linear extrapolation; it reflects the compounding effect of technology penetration, regulatory pressure, and the operational economics of precision construction and extraction workflows.
At the heart of this projection sits a CAGR of 24.54%, a figure that signals both opportunity and planning discipline. Growth at this pace reshapes competitive positioning quickly, compresses the window for first-mover advantage, and requires organizations to make simultaneous bets across product configuration, dealer enablement, data services, and aftertreatment strategy. The full report unpacks the structural drivers behind this expansion, but for 2026 planning purposes, the central takeaway is clear: intelligent excavators are moving from niche differentiation to mainstream operational necessity.
The study also situates this growth within a concentrated competitive environment. With the top three players accounting for 53.8% of market revenue and the top five reaching 70.0%, scale, brand trust, and technology ecosystems matter. Concentration of this magnitude shapes everything from pricing dynamics and channel access to the willingness of end users to adopt new machine control platforms. Executive teams need to understand not just how large the market is, but how decisively incumbents and challengers are competing within it.
Intelligent Excavator Market
Industrial Dynamics: Forces Reshaping the Intelligent Excavator Landscape
Strategic planning in this market cannot be reduced to size and growth alone. The intelligent excavator space is being reshaped by simultaneous regulatory, operational, and cost pressures that influence product design, total cost of ownership, and procurement behavior. A thorough 2026 strategy must account for these forces as first-order variables rather than background noise.
Regulative evolution is a defining factor. Advanced emission norms such as EU Stage V, US Tier 4 Final, and China VI require sophisticated aftertreatment architectures including diesel oxidation catalysts, diesel particulate filters, selective catalytic reduction, and urea dosing systems. These requirements increase upfront equipment complexity and cost for manufacturers, while also influencing service intervals, maintenance expectations, and operator training. At the same time, stricter site safety standards are strengthening demand for smart features that support operator protection and operational compliance. In this context, intelligence is no longer limited to productivity; it is increasingly tied to risk reduction, regulatory readiness, and site governance.
Cost and labor dynamics add further strategic tension. Volatility in raw material pricing raises equipment costs and puts pressure on producer margins, forcing manufacturers and distributors to balance specification upgrades with commercial viability. Concurrently, shortages of skilled operators limit effective equipment utilization and project efficiency, especially in environments where precision digging and controlled earthmoving are essential. These constraints are not purely operational; they directly affect the appeal of intelligent features such as semi-automatic control, machine guidance, and automated tilt and rotation assistance, because such technologies can offset labor scarcity and reduce reliance on highly specialized manual proficiency.
Taken together, these dynamics create a market where technology, regulation, and workforce realities intersect. The full study examines how these forces influence segment behavior across regions, machine types, and application areas without exposing the granular splits here. For leadership teams, the strategic implication is that 2026 decisions should be modeled around total value rather than purchase price alone, factoring in compliance costs, operator availability, uptime expectations, and the potential for intelligent features to stabilize project execution.
Competitive Configuration: Leaders, Systems, and Recent Moves
Market concentration and product differentiation define the competitive battleground for intelligent excavators. The landscape includes global manufacturers, regional specialists, and technology providers whose machine control platforms increasingly matter alongside the hardware itself. PW Consulting's analysis maps this ecosystem through company profiles, solution architectures, and recent commercial activity, enabling leaders to see not only who competes, but how competition is being expressed.
Several firms stand out for their intelligent excavator propositions. SANY America offers intelligent excavator models including the SY335 medium hydraulic excavator with load-sensing hydraulic systems and advanced operator display, reflecting a product strategy that emphasizes hydraulic efficiency and machine visibility. Komatsu produces intelligent excavators such as the PC220LCi-12 featuring integrated sensors and 3D design data for precision grading and reduced rework, positioning data-driven accuracy as a core value proposition. Caterpillar provides intelligent excavator solutions with advanced electrohydraulic systems and touchscreen interfaces for efficient operation, reinforcing the role of control architecture and operator interface design. Volvo Construction Equipment manufactures smart excavator models with machine guidance, Dig Assist, and electrohydraulic controls for precision digging, aligning product capability with site-level productivity and operator support.
Regional and technology-focused players are equally important. Doosan offers smart excavators like the DX225LC-7X with 2D machine guidance, semi-automatic control, laser receiver, and e-fence virtual wall, highlighting the convergence of guidance technology and boundary management. Hyundai Construction Equipment supplies smart excavators such as the R130 SMART and R85A SMART equipped with intelligent control systems, extending the reach of connected machine architectures in competitive export and domestic markets. XCMG Construction Machinery develops intelligent excavators including remote-controlled models with self-learning functions, pointing toward automation and adaptive machine behavior as emerging differentiators. CASE Construction Equipment delivers intelligent excavator models with integrated real-time blade control and operator assistance systems, reinforcing precision and operator workflow integration. Leica Geosystems provides the Leica MC1 machine control platform with CoPilot for automatic tilt and rotation control on excavators to improve efficiency and accuracy, underscoring the strategic role of third-party machine control technology in shaping end-user outcomes.
Recent commercial activity illustrates how quickly this landscape is moving. In March 2026, SANY America formally introduced the SY335 medium hydraulic excavator featuring load-sensing hydraulics, ROPS/FOPS-certified cab, advanced operator display, and Cummins L9 Stage V/T4F engine at ConExpo-CON/AGG 2026. Around the same period, Komatsu showcased its PC220LCi-12 intelligent excavator with integrated sensors and 3D design data at CONEXPO-CON/AGG 2026 to support excavation to grade with greater precision and reduce rework. These moves are not isolated product announcements; they signal a competitive tempo in which intelligent capability, emissions compliance, and operator experience are being advanced in parallel.
For enterprise strategists, the competitive analysis in the full report goes beyond company descriptions. It connects product positioning to market structure, regional reach, and technology differentiation, helping leaders assess where partnership, procurement, or competitive response is most likely to create durable advantage. Detailed segmentation splits are reserved for the complete study so that leadership teams can explore the data with the context required to interpret it correctly.
Report Content: What Decision-Makers Will Find Inside
The full Intelligent Excavator Market study is structured for applied decision-making. It integrates market sizing, structural analysis, competitive profiling, and operational context into a single intelligence framework. The intent is to support planning in product strategy, procurement, channel development, technology investment, and risk management.
Key components of the report include:
- Market sizing from 2020 through 2032, anchored on a 2025 base year and expressed in USD million, with forecast projections that map the growth path from $2.69 million in 2026 to $9.76 million in 2032.
- A market concentration assessment showing the share held by leading players, helping executives understand competitive density and the relative weight of major incumbents.
- Segment-level analysis across regions, machine types, and application areas, presented with the depth needed to identify where intelligent excavator demand is forming and how it is distributed.
- Company profiles and solution summaries for core participants, including attribute-level detail on machine control capabilities, operator interfaces, and technology differentiators.
- A review of recent developments and product activity, including launch and showcase events that reveal the current pace of innovation and market signaling.
- An integrated discussion of market dynamics, including emission regulation, safety standards, raw material cost volatility, and skilled labor constraints, tied directly to intelligent excavator planning.
Each section is designed to be actionable. For instance, the competitive section supports vendor evaluation and partnership selection; the dynamics section supports total cost modeling and compliance planning; and the sizing framework supports capacity, investment timing, and market entry decisions. By presenting the market as a connected system rather than a collection of isolated metrics, the study helps leaders align commercial strategy with the realities of how intelligent excavators are bought, specified, and used.
Strategic Implications for 2026 Planning
For leadership teams entering 2026, the intelligent excavator market presents a clear mandate: strategy must be informed by both growth ambition and structural complexity. The rapid expansion reflected in the forecast trajectory makes this a sector where delay can be costly, but the concentration profile and regulatory environment make it equally important to move with precision. A rushed investment in the wrong configuration, channel, or technology bundle can lock in disadvantage just as quickly as early commitment can secure advantage.
The study supports several core planning priorities. First, it helps organizations assess where intelligent functionality delivers the strongest operational return, particularly in contexts where grade accuracy, rework reduction, operator scarcity, and compliance requirements are most acute. Second, it provides a basis for evaluating competitive positions and technology ecosystems, enabling better judgments about procurement, supplier selection, and collaboration with machine control providers. Third, it frames the market in terms of total cost and risk, ensuring that emission compliance, aftertreatment complexity, raw material exposure, and operator availability are treated as strategic variables rather than isolated cost items.
Importantly, the report is built to support decisions at multiple levels. Executive teams can use it to set direction and prioritize investment; product and engineering leaders can use it to benchmark intelligent capabilities and identify differentiation opportunities; and commercial and procurement teams can use it to structure sourcing and market engagement with greater clarity. The analysis is broad enough to inform enterprise strategy and detailed enough to guide operational follow-through.
Conclusion: From Signal to Decision
The Intelligent Excavator Market is expanding at a pace that demands disciplined intelligence, not intuition alone. Growth from $0.7 million in 2020 to a projected $9.76 million by 2032, with a CAGR of 24.54%, signals a market in which technology-enabled excavators are becoming central to competitive construction, transportation, mining, and specialized applications. Yet scale alone does not tell leaders where to act. Concentration, regulation, cost volatility, operator scarcity, and product differentiation all shape the practical choices that determine success in 2026 and beyond.
This article has previewed the strategic architecture of the PW Consulting study: the macro trajectory, the dynamic forces, the competitive landscape, and the operational content designed for applied decision-making. What it has not done is reveal the full segment-level detail that makes the analysis directly usable for specific planning scenarios. That deeper intelligence resides in the complete report, where regional nuance, type-level comparison, application-level distribution, and company-level positioning are presented together with the analytical context needed to act on them.
For executives who need to move from signal to strategy, the full market research provides the structured view required to make 2026 decisions with confidence. The opportunity is substantial, the competitive tempo is accelerating, and the cost of incomplete information is rising. PW Consulting's Intelligent Excavator Market study is built to close that gap.
Excavator Market
For detailed analysis of this topic, please visit the official page: Intelligent Excavator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dispensing Systems Market Hits $57.99B in 2025, Projects 6.7% CAGR Through 2032
By PW Consulting, 2026-09-16
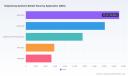
Strategic Precision: Navigating the Dispensing Systems Market Trajectory Through 2032
The global dispensing systems market is entering a decisive growth cycle, driven by tightening quality standards, the rise of automated production, and accelerating demand across high-tech manufacturing verticals. As organizations plan capital allocation and technology roadmaps for 2026 and beyond, understanding where the market is heading—and which capabilities will separate leaders from laggards—has become a critical competitive advantage. Our latest Dispensing Systems Market research study provides a structured, forward-looking intelligence framework designed to support executive decision-making through the 2026–2032 forecast horizon.
Why 2026 Marks a Strategic Inflection Point
The market has moved steadily from 41.9 billion USD in 2020 to approximately 58.0 billion USD in 2025, reflecting sustained expansion across multiple industrial and life sciences applications. The projected trajectory continues with a forecast valuation near 59.8 billion USD in 2026, progressing toward roughly 89.1 billion USD by 2032. With a compound annual growth rate of 6.7 percent, this is not a market defined by sudden volatility but by compounding structural demand. For strategic planners, that consistency is both an opportunity and a warning: steady growth rewards early positioning, but it also intensifies competition for market share as incumbents scale and new entrants refine niche technologies.
Dispensing Systems Market
Several cross-currents are reshaping how companies think about dispensing investments this year. Precision fluid control is no longer a back-office manufacturing concern. It is increasingly tied to product reliability, regulatory compliance, yield improvement, and ultimately brand credibility. In medical device assembly, electronics encapsulation, and pharmaceutical filling, consistency is not optional. Stringent quality and product consistency requirements enforced by FDA and ISO standards are pushing manufacturers toward dispensing solutions that can deliver repeatable performance under stringent inspection regimes. At the same time, advancements in robotics, closed-loop control, and integrated work cells are expanding what automated dispensing can achieve on high-mix production lines.
This is exactly why a 2026-focused intelligence view matters. Executive teams need more than a headline growth figure. They need context on how demand is shifting across system types, where adoption is accelerating, and which operational pressures are turning dispensing from a component purchase into a strategic capability.
What This Research Delivers: An Executive-Level Roadmap
Our Dispensing Systems Market study is built as a decision-support platform rather than a static data sheet. It translates macro growth signals into actionable insight across technology, application, and competitive dimensions, giving leaders a clearer line of sight into where to invest, consolidate, or differentiate.
The report examines the evolving architecture of dispensing solutions, including manual, automated, and robotic system categories. Rather than treating these as isolated product groups, the analysis maps how each category fits into different manufacturing environments, volume profiles, and precision requirements. That distinction is essential because the value proposition of a dispensing system changes depending on whether the priority is flexibility, throughput, repeatability, or contamination control.
The research also explores demand patterns across major end-use environments, including electronics, automotive, healthcare and pharmaceutical, aerospace, and packaging applications. These sectors are not moving in lockstep. Some are being pulled forward by miniaturization, sensor proliferation, and advanced assembly requirements. Others are being reshaped by traceability mandates, sterile processing expectations, or the need to handle higher-viscosity materials with greater control. The study breaks down those dynamics so strategy teams can identify which application pockets offer the strongest alignment with their own capabilities and which carry higher barriers to entry.
Beyond segmentation, the report evaluates the operational and regulatory forces that are quietly redefining competitive requirements. In life sciences and pharmaceutical production, dispensing equipment increasingly must support aseptic processing, containment discipline, and sterile drug production workflows. In medical device manufacturing, quality consistency and documentation rigor have become embedded in procurement criteria. In electronics and related high-precision sectors, the push for finer deposits, lower waste, and tighter process control is accelerating adoption of more sophisticated dispensing equipment. These trends are not abstract compliance issues; they directly influence purchasing criteria, vendor selection, and long-term service expectations.
Competitive Landscape: Where Consolidation and Differentiation Converge
The market remains concentrated, with a small group of established players commanding a significant share of revenue. That concentration matters because it shapes pricing power, technology diffusion, and partnership dynamics. Companies that can combine precision engineering, application-specific know-how, and strong service networks are well positioned, while those relying on commoditized hardware face increasing pressure.
Several firms stand out for their focus on differentiated dispensing technologies and target vertical expertise. Nordson EFD continues to emphasize precision fluid dispensing systems, automated robotic dispensers, and single-use packaging for manufacturing applications. Its recent activity underscores the importance of live demonstration and application-specific positioning, including automated fluid dispensing systems presented for medical device assembly and encapsulation, as well as demonstrations focused on wearable medical technology sensor encapsulation. That pattern illustrates a broader industry shift: competitive advantage is increasingly earned through application proof points, not specification sheets alone.
Fisnar remains focused on fluid dispensing equipment, valves, and integrated robot work cells for adhesives, resins, and industrial liquids, reflecting the continuing importance of modular, integration-ready architectures. Musashi Engineering contributes a strong precision orientation, with emphasis on liquid dispensing systems and ultra-micro control equipment for industrial manufacturing environments where minute fluid handling matters. Fluid Metering, Inc. differentiates around valveless ceramic metering pumps and dispensers designed for precise fluid control in lab, chemical, and industrial applications—an approach that highlights the role of pump and metering technology in achieving consistent output.
GPD Global targets high-performance fluid dispensing systems for electronics, PCB, semiconductor, and solar manufacturing, sectors where process discipline and contamination sensitivity reward specialized solutions. In the pharmaceutical and sterile production space, Comecer concentrates on aseptic dispensing and filling systems for pharmaceutical, radiopharmaceutical, and sterile drug production. Its recent tabletop dispensing system announcement for standalone filling and closing of injectable and non-injectable vials points to the growing demand for compact, flexible solutions that still meet stringent sterile processing requirements.
The competitive field also includes firms with strong customization and application-engineering capabilities. Hernon Manufacturing focuses on custom adhesive dispensing systems, valves, and integrated solutions for high-viscosity manufacturing, while GP Reeves builds around customized automated fluid dispensing systems for production and assembly lines. SPEC, Inc. brings a specialized emphasis on ink dispensing systems and integrated mixing equipment for coatings and industrial applications, and JagCo contributes automated adhesive, fluid, and robotic dispensing systems for manufacturing precision. Together, these players illustrate a market where broad capability and vertical specialization are both viable paths—but only when paired with convincing integration, service, and process validation support.
Recent activity across these companies reinforces a clear theme. Trade show demonstrations, product announcements, and application-focused showcases are increasingly oriented toward real-world performance in regulated or high-precision environments. That suggests the market is maturing from hardware comparison toward solution validation. Buyers are less interested in whether a system can dispense, and more interested in whether it can do so consistently within their specific process constraints.
Market Dynamics Shaping 2026 Decisions
A few strategic dynamics will influence how companies prioritize dispensing investments over the next several years.
Dispensing Robot Market
- Regulatory and quality pressure is becoming a demand catalyst. In medical device manufacturing and electronics production, expectations for quality, traceability, and product consistency are tightening. That environment favors dispensing systems with stronger process control, repeatability, and validation support.
- Automation is moving from efficiency tool to precision enabler. As labor constraints, variability, and throughput demands intensify, automated and robotic dispensing solutions are increasingly evaluated for their ability to reduce variability and support complex assembly or encapsulation tasks.
- Application specialization is reshaping purchasing criteria. Different verticals impose different constraints on viscosity handling, contamination control, deposit size, speed, and documentation. Companies that can align system design with those constraints gain an advantage in qualified supplier lists and repeat sourcing.
- Sterile and aseptic processing requirements are elevating the importance of integrated system design. In pharmaceutical and life sciences environments, dispensing equipment is being assessed not only on dispensing accuracy but also on cleanliness, containment, and compatibility with sterile workflows.
- Demonstration-led commercialization is gaining importance. Recent product showcases and live demonstrations suggest that the market values tangible proof of performance in target use cases, especially where failure is costly or compliance exposure is high.
For strategy teams, the implication is straightforward. Dispensing investment decisions should be evaluated not just against unit cost, but against compliance readiness, integration complexity, application fit, and long-term serviceability. In many cases, the most cost-effective system on paper is not the most strategically sound choice once total operating risk is considered.
How to Use This Intelligence for 2026 Planning
This Dispensing Systems Market research study is designed to support multiple planning functions. For portfolio and product teams, it provides a structured view of where demand is expanding and where application requirements are becoming more demanding. For operations leaders, it helps frame the trade-offs between manual, automated, and robotic approaches in different production contexts. For commercial and business development teams, it offers a way to benchmark competitive positioning, identify emerging solution expectations, and prioritize the verticals most aligned with organizational strengths.
The report also supports scenario thinking. Because growth is projected to persist through 2032, companies can use the analysis to test whether their current capabilities will be sufficient as requirements tighten, or whether they need to invest earlier in precision control, automation integration, or regulatory-aligned system design. The goal is not simply to forecast size, but to improve decision quality under uncertainty.
Why the Full Study Matters
Macro figures tell part of the story, but they do not reveal which segments are driving momentum, how technology preferences are shifting, or where competitive intensity is most likely to compress margins. They do not show which application requirements are becoming disqualifying factors, or how leading companies are translating regulatory and precision demands into differentiated offerings. Those insights require a deeper, more structured examination.
The complete report goes further by mapping market structure, competitive positioning, application-specific demand signals, and the operational forces that will shape purchasing behavior through the end of the decade. For teams preparing 2026 investment decisions, supplier strategies, or technology roadmaps, that level of detail is essential.
If your objective is to move beyond surface-level market sizing and understand where precision dispensing is heading, the full study offers the analytical depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Dispensing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Bio Methanol Market to Reach $215M in 2025, Growing at 8.1% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Bio Methanol Transition: Why the 2026 Market Landscape Demands Precision
The global energy and chemical transition is entering a decisive phase. As regulatory frameworks tighten and capital allocation shifts toward low-carbon alternatives, bio methanol has emerged as a critical bridge fuel and chemical building block. For executives navigating supply chain restructuring, fleet decarbonization mandates, and feedstock security, understanding the trajectory of this market is no longer optional. The latest research from PW Consulting provides a comprehensive, data-driven blueprint of the bio methanol sector, calibrated specifically to inform enterprise strategy across the 2026 to 2032 forecast horizon.
Drawing on rigorous primary analysis and validated market modeling, this study maps revenue trajectories, competitive positioning, feedstock economics, and application-level demand signals. The market size stood at approximately USD 215.0 million in 2025 and is projected to reach USD 233.57 million in 2026, expanding to USD 344.8 million by 2032. This progression reflects a compound annual growth rate of 8.1 percent, signaling sustained structural demand rather than short-term volatility. The report is designed for strategic decision-makers who require actionable intelligence on where capital, partnerships, and operational capacity should be deployed to capture value in an increasingly regulated and competitive environment.
Market Trajectory and Revenue Architecture
The historical baseline from 2020 through 2025 reveals a market that has absorbed supply chain disruptions, feedstock price variability, and early-stage regulatory uncertainty while maintaining a clear upward trajectory. Revenue expanded from USD 163.15 million in 2020 to USD 200.52 million in 2024, before stepping to the 2025 baseline of USD 215.0 million. The forecast period begins with a measured acceleration in 2026 and compounds steadily through the end of the decade, reaching USD 311.71 million in 2030 and USD 344.8 million in 2032.
This growth profile underscores a transition from pilot-scale experimentation to commercial deployment. The 8.1 percent CAGR reflects the compounding effect of regulatory tailwinds, expanding vessel and transportation decarbonization requirements, and the maturation of renewable hydrogen and biomass integration pathways. Decision-makers evaluating market entry, capacity expansion, or offtake agreements will find the forecast architecture particularly useful for stress-testing investment cases across multiple demand and cost scenarios. The study deliberately avoids superficial headline numbers, instead providing the structural logic behind each forecast milestone so that strategy teams can align their models with realistic adoption curves and feedstock availability constraints.
Report Scope and Actionable Intelligence
The research is structured to serve operational, commercial, and corporate development functions simultaneously. Rather than offering isolated statistics, the report integrates macro-level sizing with granular segmentation logic, regulatory mapping, and competitive benchmarking. The scope encompasses the full value chain from feedstock sourcing through production economics, distribution considerations, and end-use demand dynamics. Key sections include demand drivers by application category, feedstock availability and cost structures, regional market maturation patterns, and a detailed competitive landscape that maps company strategies against market share concentration and expansion roadmaps.
Each analytical module is designed to support specific business decisions. Supply chain and procurement teams can evaluate feedstock security and cost variability, while commercial leaders can assess demand intensity across marine, transport, and chemical feedstock channels. Corporate development and M&A professionals will find the competitive mapping and recent transaction activity particularly relevant for identifying partnership opportunities, capacity constraints, and consolidation trends. The report also includes forward-looking signals on pricing mechanisms, certification frameworks, and regulatory milestones that directly affect project economics and offtake structuring.
Competitive Landscape and Strategic Positioning
The bio methanol market is characterized by a moderately fragmented structure with meaningful concentration among established producers and an expanding cohort of specialized renewable fuel developers. The study highlights several core companies that are shaping commercial-scale production, technology adoption, and geographic expansion. Södra has pioneered commercial-scale production of bio-methanol from forest biomass at the Mönsterås pulp mill facility, demonstrating the viability of integrated forestry-to-fuel pathways. Enerkem operates commercial-scale waste-to-bio-methanol facilities, including the first commercial Edmonton plant and expansions such as Ecoplanta in Spain producing hundreds of thousands of tonnes annually, positioning it at the center of municipal and industrial waste conversion strategies.
Biodiesel Market
Methanex Corporation has moved aggressively into low-carbon production by acquiring OCI's methanol business and progressing renewable methanol capacity, including 40,000 to 60,000 tonnes annually from renewable natural gas at Geismar starting between 2025 and 2028. Proman continues to develop renewable methanol production sites globally with a focus on bio- and low-carbon methanol alongside broader methanol and energy operations. BASF SE is producing bio-methanol utilizing sustainable feedstocks as part of its portfolio of low-carbon chemical solutions, aligning chemical feedstock demand with decarbonization targets. Carbon Recycling International Inc. converts CO2 into sustainable methanol with production capacity exceeding 200,000 tonnes per year, representing a leading pathway in carbon capture utilization. OCI N.V. operates bio-methanol production facilities, including the BioMCN site, with a clear focus on low-carbon methanol expansion.
Market concentration metrics place the top three players at 28.4 percent and the top five at 35.2 percent, indicating room for new entrants while rewarding scale, feedstock access, and certification capability. Recent corporate activity reinforces this pattern. In October 2025, Methanex Corporation completed the acquisition of OCI Global's international methanol business, including facilities positioned for low-carbon and renewable methanol expansion. In May 2025, European Energy began commercial production of e-methanol at the Kassø facility, the world's first large-scale commercial e-methanol plant with 42,000 tonnes annual capacity. In July 2025, Platts launched daily price assessments for certified UK waste biomethane Guarantees of Origin starting 1 September 2025, creating a more transparent feedstock pricing reference point. These developments illustrate how consolidation, technology diversification, and pricing infrastructure are converging to reshape competitive dynamics.
Regulatory Drivers and Demand Catalysts
Regulatory momentum is a defining feature of the current market cycle. The FuelEU Maritime Regulation entered into force in 2025 with phased GHG intensity targets for ships, with full inclusion effective in 2026, directly strengthening the case for renewable marine fuels. Alongside this, the EU ETS phases in 40 percent in 2024, 70 percent in 2025, and 100 percent in 2026 for shipping emissions, increasing the economic cost of fossil-based operations and improving the relative attractiveness of low-carbon alternatives. These frameworks are not abstract policy signals; they translate into fleet planning decisions, fuel procurement strategies, and long-term charter economics.
Feedstock economics also shape market outcomes. Biomethane production costs exhibit a wide range, with 90 percent of potential between USD 10 per GJ and USD 30 per GJ, making feedstock selection, sourcing geography, and certification quality central to project viability. The launch of UK waste biomethane price assessments for RGGOs, with daily pricing starting 1 September 2025 and covering carbon intensity from 0 to 25 g CO2e/MJ, adds a critical layer of transparency for producers and buyers negotiating renewable feedstock contracts. For chemical and transportation end-users, these developments create both compliance obligations and commercial opportunities, particularly for organizations that can secure certified supply early and integrate lifecycle carbon accounting into procurement decisions.
Segmentation Logic and Strategic Implications
The report's segmentation framework is built to help executives identify where demand intensity, feedstock suitability, and regional readiness intersect. The analysis separates market dynamics by geographic maturity, feedstock pathways, and application channels, allowing strategy teams to evaluate which segments offer the most favorable risk-adjusted returns under current regulatory and cost conditions. Rather than presenting static percentage splits, the study explains the underlying logic of segment performance, including the influence of waste availability, biomass logistics, renewable natural gas access, and certification requirements on commercial viability.
This approach is especially valuable for companies deciding where to allocate development capital or negotiate offtake agreements. Marine fuel demand is shaped by maritime decarbonization mandates and vessel retrofit cycles. Transportation applications depend on fuel infrastructure readiness and regional incentive structures. Chemical feedstock demand reflects the broader shift toward sustainable inputs in industrial supply chains. By connecting segment behavior to regulatory timelines, feedstock economics, and producer capacity pipelines, the report enables more precise scenario planning and portfolio prioritization.
Bio Methanol Market
Why This Study Matters for 2026 Decision-Making
2026 represents a pivotal year for strategic positioning in the bio methanol market. Regulatory mandates become fully operational, pricing references mature, and commercial-scale projects move from construction to ramp-up. Organizations that wait for perfect clarity risk entering the market at higher cost or without secured feedstock and offtake alignment. The PW Consulting study is designed to reduce that uncertainty by providing a structured, evidence-based view of market size, growth drivers, competitive moves, and segment-level demand logic.
The report equips leadership teams with the context needed to evaluate investment timing, partner selection, and capacity strategy. It also serves as a reference point for aligning internal assumptions with external market realities, particularly around carbon intensity requirements, feedstock cost variability, and consolidation activity. Because the study emphasizes decision-useful structure over raw data dumps, readers can translate findings directly into operational roadmaps, procurement strategies, and commercial positioning.
For organizations seeking a complete view of the forecast tables, regional and feedstock-level segmentation detail, application demand breakdowns, and full company profiles with expansion roadmaps, the full report is available through the PW Consulting research portal. The complete dataset and accompanying analytical modules are intended to support precise modeling, strategic planning, and confident execution throughout the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Bio Methanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pharmaceutical Autoclaves Market to Hit $448M by 2032, 4.68% CAGR
By PW Consulting, 2026-09-16
The Imperative for Sterility: Strategic Outlook for the Pharmaceutical Autoclaves Market 2026-2032
Executive Overview
In the landscape of pharmaceutical manufacturing, the autoclave is not merely a piece of equipment; it is the guardian of product integrity. As the industry navigates a period of heightened regulatory scrutiny, complex production pipelines, and geopolitical supply chain realignments, the demand for reliable steam sterilization has never been more critical. Our newly released comprehensive study on the Pharmaceutical Autoclaves Market provides the intelligence required to maneuver this essential segment. With a projected market valuation reaching significant milestones by the end of the decade, understanding the trajectory of this sector is paramount for capital allocation, capacity planning, and competitive positioning.
The historical trajectory from 2020 through 2025 demonstrates a resilient growth pattern, establishing a robust baseline for the forecast period extending to 2032. This market research is designed not just to report figures, but to translate them into actionable strategic directives. For stakeholders facing procurement decisions in 2026, the difference between cost-effective efficiency and operational compromise often lies in the nuanced understanding of market dynamics, technological advancements, and regulatory pressures detailed within this report.
Market Trajectory and Structural Insights
The growth narrative for pharmaceutical autoclaves is defined by steady expansion driven by the foundational need for sterile processing. Following a historical phase where the market solidified its value well above the $250 million mark, the forecast period indicates a sustained Compound Annual Growth Rate of 4.68%. This consistent progression suggests that despite macroeconomic fluctuations, the core requirement for validated sterilization in pharma manufacturing remains inelastic. By 2032, the market value is expected to reflect the cumulative impact of infrastructure upgrades and capacity expansions initiated in the mid-2020s.
Analysis of capacity segmentation reveals critical operational insights for manufacturers. While smaller unit capacities under 200 liters maintain a presence suitable for specific laboratory applications, the segment spanning 200 to 1000 liters represents a substantial portion of revenue generation. Furthermore, high-capacity units exceeding 1000 liters command a significant share, reflecting the industry-wide trend toward large-scale biopharmaceutical production and fill-finish operations. This bifurcation suggests a market that serves both specialized research needs and massive commercial manufacturing scales, requiring distinct procurement strategies for different organizational tiers.
Revenue distribution across applications further underscores the breadth of opportunity. Pharmaceutical companies constitute the dominant application segment, leveraging sterilization for terminal sterilization processes and aseptic filtration support. Pharmaceutical laboratories form the secondary but vital pillar, utilizing these systems for R&D validation and small-batch production. The interplay between these two segments indicates that demand is not solely dependent on commercial drug launch volumes but is also buoyed by sustained investment in early-stage drug discovery and process development.
Regulatory Pressures and Operational Dynamics
The regulatory environment is a primary catalyst reshaping procurement cycles and equipment specifications. A pivotal development occurred in 2024 when ISO 17665:2024 regarding moist heat sterilization validation gained FDA recognition. This standard mandates full compliance for pharmaceutical equipment by 2027. This timeline creates an immediate urgency for manufacturers to audit existing sterilization capabilities. Those relying on legacy equipment or non-compliant validation protocols face a compressed window to upgrade, driving demand through the forecast period.
Beyond specific standards, the broader push for digital compliance is altering equipment preferences. Industry market data suggests that over 67% of hospitals prioritize automated steam sterilizers with digital compliance tracking to meet reimbursement standards for infection control. While this statistic originates from the hospital sector, it creates a spillover effect in pharmaceutical manufacturing where data integrity and traceability are increasingly scrutinized by regulatory bodies. Consequently, integration of automated data traceability features is becoming a differentiator rather than a luxury.
Biopharmaceutical Biopharma Autoclaves Market
Infrastructure modernization is another key dynamic. More than 10,000 pharmaceutical sites upgraded sterilization units between 2023 and 2025 to align with new GMP and FDA standards. This wave of upgrades suggests a market moving from a replacement cycle to a modernization cycle, where efficiency, energy consumption, and footprint are evaluated alongside basic sterilization efficacy. However, modernization comes with cost implications. The reliance on stainless steel and advanced alloys for chambers and components contributes to higher material costs, pressuring margins and influencing total cost of ownership calculations for buyers.
Competitive Dynamics and Key Player Strategies
The market concentration indicates a moderately consolidated landscape. The top three entities hold a combined share of 48%, while the top five control 64%. This structure suggests room for niche players to thrive through specialization while allowing larger incumbents to leverage scale for service networks and R&D investment.
Strategic Profiles of Market Leaders
STERIS Corporation (Mentor, Ohio, United States) continues to anchor its position through comprehensive steam sterilizers and integrated sterilization equipment. Their focus on digital validation for pharmaceutical terminal sterilization ensures alignment with GMP compliance, making them a preferred partner for large-scale regulated facilities. In mid-2024, the company expanded its pharmaceutical sterilization support services across North America and Europe, deepening client stickiness through after-sales engagement rather than just hardware sales.
Getinge AB (Gothenburg, Sweden) emphasizes scalability and energy efficiency with its GMP-compliant terminal sterilizers, specifically the G-Series and GSS configurations. A notable product launch in early 2024 introduced upgraded GSS steam sterilizer configurations featuring automated data traceability. This move directly addresses the regulatory shift toward digital compliance, positioning Getinge as a forward-thinking solution provider for clients preparing for the 2027 FDA deadlines.
Belimed AG (Sulgen, Switzerland) has aggressively pursued international growth. In 2025, the company partnered with multiple Asian pharmaceutical firms, supplying a significant volume of large-capacity autoclaves tailored for vaccine manufacturing. This strategy highlights the geographic shift in manufacturing capacity and the critical role of sterilization in pandemic preparedness and vaccine supply chains. Their MST-V and PST.2 series continue to be benchmarks for energy-efficient designs.
Fedegari Autoclavi S.p.A. (Albuzzano, Italy) specializes in high-performance GMP washer-sterilizers and custom autoclaves for biopharmaceutical and sterile drug production. In 2025, the group completed construction of a new Biotech Plant in Ireland, supplied with high-performance GMP washers and autoclaves. This facility became the largest plant outside China, signaling a strategic expansion beyond Asian markets and reinforcing their capability to support large-scale global operations.
Shinva Medical Instrument Co., Ltd. (Jining, China) represents the growing influence of Asian manufacturers. In 2025, ChinDevelop independently developed and introduced the new LAS-M Series Vertical Autoclave. These high-output systems are designed for both domestic and export pharma applications, indicating a move from generic equipment to specialized, proprietary solutions that compete on both price and feature parity.
Sakura Seiki Co., Ltd. (Tokyo, Japan) and Yamato Scientific Co., Ltd. (Tokyo, Japan) focus on high-pressure steam sterilizers and washer-sterilizers engineered for validation in the pharmaceutical and food industries. Their reputation for precision engineering appeals to manufacturers where validation protocols are particularly rigorous.
Tuttnauer Ltd. (Netherlands) offers pharmaceutical line autoclaves with automatic sliding doors, featuring chamber volumes ranging from 250L to 2000L. This capacity range bridges the gap between laboratory scale and production scale, serving regulated biopharma operations that require flexibility without sacrificing regulatory adherence.
Yamato Scientific Co., Ltd. (Tokyo, Japan) provides laboratory and industrial steam sterilizers with high-performance features for aseptic processing and pharma applications, complementing the broader ecosystem of Japanese precision engineering.
Astell Scientific Ltd. (Powys, UK) is noted for square-chamber steam sterilizers ranging from 33 to 2000 liters, integrated with wastewater and effluent decontamination systems. This holistic approach addresses the full lifecycle of sterilization waste, a growing concern in environmental compliance.
DE LAMA S.p.A. (San Martino Siccomario, Italy) offers saturated steam, air-steam mixture, and HyPerPure H2O2 sterilizers with validation services for pharmaceutical and medical device manufacturing, showcasing the diversification of sterilization technologies beyond standard steam.
LTE Scientific Ltd. (Oldham, UK) and Rodwell Autoclave Company (Basildon, UK) provide multi-purpose lab and large-capacity steam sterilizers and precision laboratory and production autoclaves respectively. These players often cater to specific regional needs or specialized production requirements where customization is valued over mass production.
Strategic Implications for 2026 Decision-Making
As we move into 2026, the intersection of regulatory deadlines and capacity constraints will define the negotiation landscape for procurement leaders. Pharmaceutical manufacturing accounts for nearly 38% of total steam sterilization equipment demand. This dominance means that capital expenditure trends in the pharma sector directly dictate the market's health. With accelerated adoption of high-capacity pre-vacuum models, manufacturers must evaluate whether their current infrastructure can support the throughput requirements of next-generation biologics and sterile injectables.
The data on market concentration reveals that while the top players hold significant sway, the fragmented nature of the lower tier allows for competitive bidding opportunities. However, focusing solely on price can be hazardous given the regulatory landscape. The cost of non-compliance or validation failure far outweighs minor savings on equipment acquisition. Therefore, the strategic value of this market research lies in its ability to quantify the risk-adjusted cost of ownership.
Moreover, the geographic distribution of demand implies that supply chain resilience is a priority. With significant revenue generated across North America and Europe, alongside growing contributions from the Asia Pacific region, global sourcing strategies must account for local regulatory nuances and logistical reliability. The recent expansions by key players into Ireland and Asia indicate where the manufacturing hubs are shifting, offering clues on where to establish strategic partnerships or sourcing relationships for long-term stability.
The raw material dynamics also warrant attention. The reliance on advanced alloys for chambers and components suggests that lead times and pricing volatility may persist. Procurement teams should factor in material cost fluctuations when budgeting for capital projects in 2026 and beyond. Integrating these macroeconomic variables into the equipment selection process is essential for protecting project margins.
Pharmaceutical Autoclaves Market
Why Access the Full Intelligence
While the overview above outlines the structural currents of the market, the granular details necessary for precise execution are contained within the full report. The surface-level trajectory confirms growth, but the specific segmentation data, regional revenue splits, and detailed competitive benchmarking are essential for refining investment thesis statements. For instance, knowing the exact split of revenue by capacity tier allows for targeted R&D planning, while regional breakdowns help identify emerging markets with favorable regulatory environments.
The report also provides a deep dive into recent developments that serve as proxies for future behavior. Events such as facility expansions, specific product launches, and strategic partnerships analyzed in detail reveal the long-term strategic intents of competitors. Understanding that a key competitor has just opened a massive plant in Ireland or launched a new vertical autoclave series provides the context needed to anticipate market supply shifts and competitive responses.
Ultimately, this study serves as a bridge between high-level strategy and operational reality. It equips stakeholders with the knowledge to navigate the ISO 17665:2024 compliance timeline, the capex trends driving demand, and the competitive moves defining the industry. For executives, plant managers, and investors looking to secure a position in the Pharmaceutical Autoclaves Market through 2032, the comprehensive analysis provided in our full research offering is an indispensable tool. It transforms raw data into a roadmap for sustainable growth and risk mitigation in a sector where sterility is synonymous with success.
To access the complete segmentation analysis, detailed company profiles, and the full five-year forecast model, we invite you to review the complete market research document. This intelligence is curated to support high-stakes decision-making in the coming years.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Autoclaves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart City ICT Market Hits $215B in 2025, Forecasted to Surge to $344.8B by 2032
By PW Consulting, 2026-09-16
Navigating the Urban Intelligence Ecosystem: Strategic Imperatives for the Smart City ICT Infrastructure Market
The global urban landscape is undergoing a structural transformation driven by the convergence of digital connectivity, data analytics, and intelligent automation. As municipalities and private developers race to deploy integrated technology ecosystems, the demand for robust Information and Communications Technology infrastructure has become the cornerstone of modern urban planning. PW Consulting's latest comprehensive study on the Smart City ICT Infrastructure Market offers a critical lens through which stakeholders can interpret this accelerating evolution. This report is not merely a collection of statistics; it is a strategic compass designed to guide investment decisions, technology roadmap planning, and competitive positioning through the remainder of the decade.
Understanding the trajectory of this sector requires more than surface-level observation. It demands a rigorous examination of historical performance, forward-looking projections, and the underlying forces reshaping how cities function. The following analysis previews the depth of our findings, highlighting the market's growth narrative, the technological pillars driving adoption, the intensifying competitive arena, and the regulatory frameworks that will dictate deployment standards. For executives, investors, and policy architects, the insights contained within this research serve as an essential foundation for capitalizing on the opportunities inherent in the urbanization of intelligence.
Market Trajectory and Growth Dynamics
The economic scale of the Smart City ICT Infrastructure Market underscores its transition from a niche innovation sector to a fundamental component of global infrastructure spending. Based on a comprehensive historical analysis spanning from 2020 to 2025, the market has demonstrated consistent expansion, reflecting the increasing prioritization of digital urban solutions worldwide. In the base year of 2025, the total market revenue reached approximately 215.0 billion USD. This figure represents a significant accumulation of value over the past five years, driven by accelerated digitization initiatives and the post-pandemic emphasis on resilient urban systems.
Looking toward the forecast period from 2026 through 2032, the growth momentum is projected to sustain a robust pace. Our analysis indicates a compound annual growth rate (CAGR) of 10.39 percent over this horizon. Such a rate signals not only continued adoption but also the deepening integration of ICT layers into legacy urban systems. By 2032, the market is anticipated to expand substantially, crossing the threshold of 344.8 billion USD. This trajectory suggests that smart infrastructure will move beyond pilot phases and isolated implementations, becoming embedded in the standard operational fabric of cities across varying levels of economic development.
However, raw revenue figures only tell part of the story. The market's expansion is fueled by distinct technological and application drivers, each carrying its own risk-return profile and implementation complexity. Understanding which segments will catalyze the next wave of value creation requires a nuanced breakdown of the market architecture, which our full report delineates with granular precision. Stakeholders seeking to allocate capital or forge partnerships must look beyond the aggregate numbers to identify where the Margin of impact is highest.
Technological Pillars and Application Verticals
The Smart City ICT Infrastructure Market is characterized by a multi-layered technology stack that enables the collection, transmission, processing, and actuation of urban data. Our research dissects these layers to reveal which technologies are commanding the largest share of investment and which are poised for rapid scaling. The IoT ecosystem remains a dominant force, serving as the sensory nervous system of the smart city by connecting physical assets to digital management platforms. Complementing this connectivity layer, advancements in artificial intelligence and machine learning are transforming raw data streams into actionable insights, enabling predictive maintenance, traffic optimization, and energy efficiency.
On the application front, the deployment of ICT infrastructure is heavily concentrated in sectors that directly impact citizen quality of life and municipal operational efficiency. Smart Transportation and Mobility represents a critical vector of investment, as cities seek to alleviate congestion, reduce emissions, and enhance public transit reliability through real-time data integration. Beyond mobility, Smart Governance and Administration is emerging as a key area where ICT infrastructure supports transparent, data-driven decision-making and streamlined public service delivery. Additional applications span environmental monitoring, public safety, and utility management, each requiring specialized infrastructure configurations.
For technology providers and solution integrators, the interplay between type and application is where competitive differentiation is forged. Our report provides a detailed mapping of how specific ICT components align with high-growth application verticals, highlighting the synergies and bottlenecks that define deployment success. This level of detail is crucial for organizations aiming to tailor their offerings to the most receptive market segments and avoid the pitfalls of fragmented, non-interoperable solutions.
Competitive Landscape and Strategic Positioning
The arena for smart city infrastructure is populated by a diverse cohort of global technology leaders, each leveraging distinct heritage strengths to capture market share. Cisco, headquartered in San Jose, California, continues to anchor its strategy on robust networking capabilities, 5G platforms, and IoT connectivity solutions that form the backbone of city-wide communication grids. Their focus on data platforms for governance and service efficiency positions them as a foundational player in the infrastructure layer.
IBM brings a complementary strength in data analytics, AI, and IoT platforms tailored for infrastructure management, utilities, and transportation. Their emphasis on real-time operational insights appeals to municipal operators seeking to derive value from complex data environments. Meanwhile, Huawei delivers a comprehensive suite of ICT infrastructure, including 5G networks, cloud computing, and AI capabilities, often integrated with intelligent operation centers that support planning, security, and service optimization. Their end-to-end approach allows for tight integration across multiple urban domains.
Worldwide Modern AI Infrastructure Market
European industrial giants also play pivotal roles. Siemens offers IoT, edge computing, and digital twin solutions that integrate deeply with physical smart infrastructure, targeting urban mobility, energy, and sustainability applications. ABB focuses on power automation and smart grid technologies, providing IoT-enabled infrastructure solutions essential for efficient urban energy distribution. Honeywell rounds out this competitive set with smart sensors, analytics, and infrastructure solutions dedicated to energy management, transportation, and environmental monitoring.
Market concentration metrics indicate a competitive environment that is broad rather than monopolistic. The CR3 stands at 24.6 percent, and the CR5 at 26.2 percent, suggesting that while tier-one players hold significant influence, ample space remains for specialized vendors, regional specialists, and innovative disruptors. This fragmentation creates opportunities for strategic partnerships, M&A activity, and niche technology insertion. Our report analyzes the battleground positioning of these key enterprises, examining recent developments and strategic moves that signal where the market is heading.
Smart City ICT Infrastructure Market
Industry Dynamics: Regulation, Funding, and Standardization
The deployment of smart city ICT infrastructure does not occur in a vacuum; it is shaped by an evolving ecosystem of regulatory frameworks, public funding mechanisms, and standardization efforts. Recent legislative and institutional actions highlight the growing commitment of governments to accelerate digital urban transformation. In the United States, legislative measures such as H.R.4649 have authorized significant appropriations to support smart city and community technology developments, including broadband infrastructure, signaling a long-term fiscal commitment to closing the digital divide and enabling advanced urban services.
In Europe, the European Commission has bolstered support through pilot project funding, allocating additional resources for digital infrastructure deployment and AI-enabled services across energy and mobility sectors in smart cities and rural communities. These initiatives are complemented by broader programs like the Digital Europe Programme, which fosters large-scale pilots aimed at strengthening data infrastructure and intelligent services. Furthermore, cross-border recognition of successful implementations is evident in award programs that highlight operational projects delivering measurable impact, reinforcing best practices and driving replication.
Standardization bodies are also actively working to bring coherence to the fragmented landscape of smart city technologies. Initiatives such as ISO/IEC AWI 21252 and ISO/IEC PWI 5217 are under development to provide guidance on ICT infrastructure planning and digital infrastructure design, respectively. Additionally, ETSI TC ATTM is advancing standards for sustainable digital multi-service cities. These standardization efforts are critical for ensuring interoperability, security, and sustainability, and they will increasingly influence procurement criteria and vendor selection. Organizations that align their strategies with emerging standards will gain a distinct advantage in compliance-driven markets.
Strategic Value for 2026 Decision-Making
For enterprise leaders and investors, the 2026 horizon represents a inflection point where early experimentation gives way to scaled deployment and commercial maturity. The strategic value of this research report lies in its ability to translate market intelligence into actionable decision frameworks. By synthesizing historical data, forward-looking forecasts, segmentation analysis, and competitive intelligence, the report enables stakeholders to:
- Identify high-growth segments and prioritize investment based on verified market sizing and growth rates.
- Anticipate competitive shifts and evaluate partnership or acquisition opportunities among key players.
- Navigate regulatory and standardization developments to mitigate compliance risks and align product roadmaps.
- Understand the macroeconomic and regional drivers that will shape demand across different geographies.
- Leverage funding trends and public-sector initiatives to inform go-to-market strategies and business development.
The full report goes beyond the executive overview to deliver the granular data, detailed company profiles, and scenario-based analysis required for robust strategic planning. It provides the comprehensive intelligence necessary to make informed choices in a market defined by rapid technological change and complex stakeholder dynamics. Readers are encouraged to access the complete repository of insights to secure a decisive edge in navigating the smart city ICT infrastructure landscape.
For detailed analysis of this topic, please visit the official page: Smart City ICT Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com